Buy now, pay later (BNPL) is everywhere at checkout now: Afterpay, Klarna, Affirm and plans built right into your bank’s credit card. Splitting a $240 purchase into four $60 payments feels painless. But one question comes up again and again: does buy now, pay later affect your credit score in Canada?
It’s a timely question. In an Equifax Canada survey released in August 2026, 29% of Canadians said they’re using more credit for essentials like groceries and utilities. When budgets are stretched, it’s worth knowing exactly how BNPL can help or hurt your credit.
The short answer
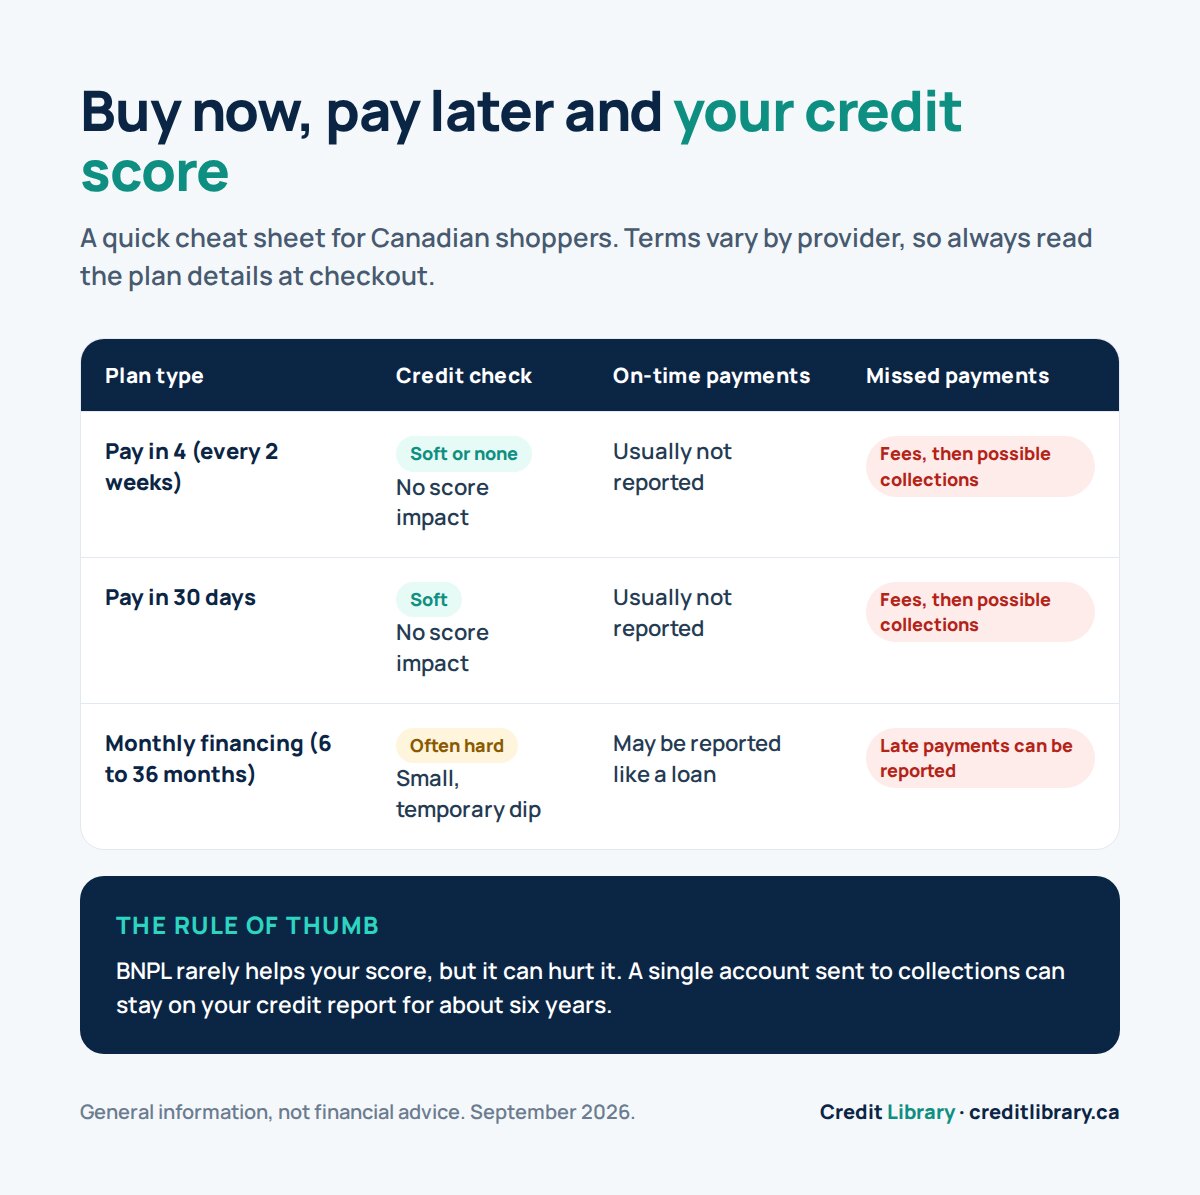
- Short pay-in-4 plans usually use a soft check (or none) and usually aren’t reported to Canadian credit bureaus when you pay on time. They generally won’t raise or lower your score.
- Longer monthly financing often involves a hard credit check and can be reported like any other loan.
- Missed payments are the real risk. Late fees come first, but an unpaid balance can be sent to collections, which can damage your score for years.
How buy now, pay later works in Canada
BNPL comes in a few flavours, and they don’t all treat your credit the same way:
- Pay in 4: the purchase is split into four equal payments, usually every two weeks, with no interest if you pay on time.
- Pay in 30 days: you get the item now and pay the full amount within about a month.
- Monthly financing: a longer instalment loan, often 3 to 36 months, that may charge interest. Affirm, for example, shows an $800 purchase split into 12 monthly payments of $72.21 at 15% APR.
- Credit card instalment plans: many Canadian banks let you convert a card purchase into monthly instalments. These stay on your credit card, so the balance still counts toward your credit utilization.
Does buy now, pay later do a credit check?
Most pay-in-4 and pay-in-30 plans use a soft check or an internal risk assessment. Soft checks don’t affect your score, and other lenders don’t see them. Longer financing plans are more likely to use a hard check, which can lower your score by a few points for a short time and stays on your Equifax report for three years.
| Provider (Canada) | Short plans | Longer financing | On-time payments reported? |
|---|---|---|---|
| Afterpay | No traditional bureau check | Not offered | No |
| Klarna | Soft check (Pay in 4, Pay in 30) | Hard check possible | Generally only for financing |
| Affirm (formerly PayBright) | Soft check (Pay in 4) | Hard check possible | Generally only for monthly plans |
Provider policies change. Always read the credit check and reporting terms shown at checkout.
Do BNPL payments show up on your credit report?
For short plans, on-time payments usually don’t appear on Canadian credit reports. That means pay-in-4 doesn’t build your credit, even if you use it responsibly for years.
Missed payments are a different story. Providers typically charge a late fee (often up to about $10 per missed instalment) and pause your account. If the debt stays unpaid for roughly three to four months, it can be sold or assigned to a collection agency. According to Equifax Canada, a collection account stays on your report for six years from the date of first delinquency.
The hidden ways BNPL can affect your credit
Even when BNPL doesn’t show up on your credit report, it can still affect your finances and your ability to borrow:
- Stacking plans: it’s easy to lose track of several plans with different due dates. Missed payments on BNPL, or on other bills because cash went to BNPL, can hurt your credit.
- Mortgage applications: lenders review your bank statements and may treat recurring BNPL payments as debt when working out how much you can borrow.
- Credit card instalments: converting card purchases into instalments keeps the balance on your card, which can keep your credit utilization high.
- No positive history: because on-time payments usually aren’t reported, BNPL won’t help you build the track record you need for a car loan or mortgage.
Many Canadians find this confusing. In the Financial Consumer Agency of Canada’s pilot study on BNPL, users reported difficulty understanding key parts of these plans:
Is BNPL credit reporting changing?
Yes, slowly. In the U.S. and the U.K., major BNPL providers have started sharing more payment data with credit bureaus. In Canada, reporting of short pay-in-4 plans is still voluntary and inconsistent as of September 2026. Expect that to change over time, which could mean BNPL eventually helps people who pay on time, and becomes even more costly for people who don’t.
How to use buy now, pay later without hurting your credit
BNPL ground rules
Only buy what you could pay for today
If you couldn’t cover the full price from your bank account right now, BNPL is borrowing you can’t afford.
Keep it to one plan at a time
Multiple plans with different due dates are how missed payments happen.
Turn on autopay and reminders
Make sure the linked account will have enough money on each payment date.
Read the plan type
Pay in 4 and monthly financing are different products. Check for a hard credit check and any interest before you accept.
Pay off plans before big applications
Clear any open BNPL balances a few months before you apply for a mortgage or car loan.
BNPL vs a credit card: which is better for your credit?
If you pay your full statement balance every month, a credit card usually wins for building credit. On-time card payments are reported to Equifax and TransUnion, and Canadian cards from federally regulated institutions give you a grace period of at least 21 days with no interest on new purchases.
BNPL can make sense for a single planned purchase you can afford, especially at 0% interest. But if a card balance is already hard to pay down, adding BNPL on top usually makes things worse. See what minimum payments really cost before you split another purchase.
Frequently asked questions
Does Afterpay affect your credit score in Canada?
Afterpay doesn’t run a traditional credit check with Equifax or TransUnion, and it doesn’t report on-time payments to Canadian credit bureaus, so normal use won’t change your score. If you fall far behind, though, an unpaid balance can be sent to a collection agency, and that can appear on your credit report.
Does Klarna do a hard credit check in Canada?
For Pay in 4 and Pay in 30 plans, Klarna uses a soft check that doesn’t affect your score. Longer-term Klarna financing can involve a hard credit check, which may cause a small, temporary dip. Check the plan details at checkout before you agree.
Does Affirm report to credit bureaus in Canada?
It depends on the plan. Short interest-free Pay in 4 plans generally aren’t reported. Monthly Affirm financing (formerly PayBright in Canada) is a loan, may involve a hard credit check and can be reported to a credit bureau, including any late payments.
Can buy now, pay later help build my credit?
Usually not in Canada. Most short BNPL plans don’t report on-time payments, so they don’t add positive history. A credit card paid in full every month is a far more reliable way to build credit.
What happens if I miss a buy now, pay later payment?
You’ll typically be charged a late fee and your account may be paused. If the balance stays unpaid for a few months, it can be sent to collections, which can stay on your Equifax credit report for six years from the date of first delinquency.
Will using buy now, pay later affect getting a mortgage?
It can. Even if a plan isn’t on your credit report, mortgage lenders review your bank statements and may count regular BNPL payments as debt. Several open plans can also raise questions about your cash flow, so it’s smart to pay them off before you apply.
This article is general information, not financial advice. BNPL providers change their credit check and reporting practices; check the terms shown at checkout. Last reviewed September 2026.